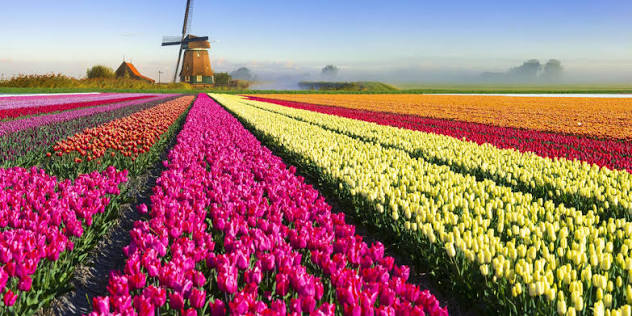
In the winter of 1636–1637, a rare tulip bulb could be sold more than once without ever leaving the ground. That fact is striking enough. It does not need the familiar embellishment that a single flower cost as much as a house, or that the collapse of bulb prices ruined the Netherlands. Those claims have made “tulip mania” a durable warning about irrational markets, but they obscure a smaller, stranger, and better documented story.
The Dutch Republic did experience a speculative rush in particular tulip varieties. Contracts changed hands rapidly; prices rose sharply in some circles; and a failed auction in February 1637 exposed how fragile the trade had become. Yet surviving legal records, account books, pamphlets, and later historical research point away from a national economic catastrophe. Tulip mania is worth understanding precisely because it shows how a limited market episode can grow into a legend about an entire society.
A flower arrived in a commercial republic
Tulips were not native to the Low Countries. Their early modern European story begins with plants and bulbs moving westward through Ottoman and Habsburg diplomatic and scholarly networks. By the late sixteenth century, collectors in the Dutch Republic were cultivating them. The flower’s appeal was not simply novelty. Its upright shape, unusually intense colors, and ability to produce distinctive patterned blooms made it a prized object in a culture that valued gardens, botanical learning, paintings, and carefully assembled collections.
Some of the most admired tulips were “broken” varieties, whose petals displayed flames, feathers, or streaks of contrasting color. Their spectacular appearance was real, but the cause was not understood at the time. Modern botany identifies tulip breaking virus as the source of many such patterns. The virus also weakened plants and made the prized varieties difficult to reproduce reliably. That combination of beauty, rarity, and uncertainty helped give individual bulbs social and commercial value.
The Republic was well suited to trade in specialized goods. Its cities had dense networks of merchants, brokers, craftsmen, shippers, and credit relationships. Amsterdam dominated long-distance commerce, but the tulip trade also involved towns such as Haarlem, Alkmaar, and Enkhuizen. It is misleading to imagine a single national tulip exchange or a modern stock market devoted to flowers. The trade was decentralized and layered: elite collectors, growers, dealers, and occasional buyers participated in different ways and at different scales.
That setting matters. Tulips became desirable within an already commercial society; they did not create Dutch capitalism, and they did not represent every Dutch household. The Rijksmuseum’s overview of tulip fever stresses this distinction between a genuine fashion and the later myth of universal madness.
Bulbs became promises during the winter
The most intense trading occurred when bulbs were in the ground, generally between late autumn and early spring. A grower could not dig up a bulb every time a buyer wanted to inspect it. Instead, participants made agreements for future delivery. Historians often call this windhandel, literally “wind trade”: the object being traded was a promise rather than a bulb passed hand to hand.
That does not make the agreements fictitious. A contract could refer to a named variety, a stated weight, and a delivery date. But it created opportunities for rapid resale. A buyer who acquired a contract in December might sell the claim to another person in January, hoping the price would rise before delivery. Small price movements could thus become visible in a chain of transactions without requiring a large physical stock of bulbs to circulate.
It is tempting to call this a futures market, but the comparison needs care. There was no centralized exchange, uniform margin system, or clearinghouse guaranteeing settlement. Local practices differed, and private agreements were supported by social reputation as much as by formal institutions. The trade used recognizable commercial techniques, yet it was neither a modern derivatives market nor merely a game played by fools.
Contemporary observers noticed the unusual character of the dealings. Some mocked the buyers; others defended the trade as ordinary commerce. Pamphlets and satirical prints supplied memorable images of amateurs crowding into taverns. Such sources are valuable evidence of anxiety and ridicule, but they are not neutral statistical reports. They show that the episode was visible enough to provoke commentary, not that every person in Holland was buying bulbs.
What rose in 1636–1637—and how far?
Price lists and sales records show that certain varieties rose dramatically in the winter of 1636–1637. The most famous names—Semper Augustus, Viceroy, and Admiral van der Eijck—still appear in accounts of the episode because rare patterned bulbs could command extraordinary sums. But a famous asking price, a reported price, and an amount actually paid are not interchangeable. Many widely repeated figures come from later compilations or satirical material rather than a complete ledger of cash transactions.
Anne Goldgar’s archival research, summarized by the University of Chicago Press, transformed discussion of this question. Her reconstruction finds a relatively small network of people whose occupations and credit arrangements were often more substantial than the familiar caricature of desperate peasants. That does not eliminate speculation. It changes its social scale and asks readers to stop treating a vivid anecdote as a national balance sheet.
Price increases also varied sharply by variety. Exceptional bulbs were scarce, and named varieties carried reputations that could travel through collector networks. Less rare bulbs did not necessarily follow the same path. The lesson is not that prices were moderate; some were emphatically not. It is that an index for “the price of tulips” did not exist, and a handful of celebrated prices cannot be used to measure the wealth of a country.
Financial historians make a related point: markets can be speculative without being irrational in every respect. Buyers may have expected future collectors to value scarcity, novelty, and distinctive appearance. Whether those expectations were sustainable was another question. The Cambridge Financial History Review has emphasized how later writers repeatedly simplified this ambiguity into a morality tale.
Why buyers vanished in February
On 3 February 1637, a Haarlem auction failed to attract buyers at a price that sellers expected. The episode became a focal point because it made a hidden problem public: a bargain has value only while someone believes it can be sold or settled. When confidence weakened, parties who had agreed to buy bulbs at high prices had every reason to hesitate.
No single documented cause explains the reversal. Disease outbreaks, especially plague, may have disrupted meetings and household finances in some towns. Seasonal timing mattered because delivery and planting approached. The sheer speed of recent price gains may also have made buyers wary. These are plausible contributing conditions, not a proven one-cause explanation. A history that says “the bubble burst because tulips were worthless” supplies a tidy answer that the sources do not justify.
The failure was especially damaging because trading had relied on expectations rather than immediate delivery. A person willing to resell a contract at a higher price might be reluctant to take the bulb and pay the original sum. Once several buyers hesitated, each seller had reason to fear the next auction. Markets built on trust can change direction quickly even when the underlying good remains attractive.
What happened in Haarlem therefore deserves more attention than it usually receives. It was not a cinematic moment in which the whole Dutch Republic discovered that flowers were absurd. It was a local signal that contracts at inflated prices might no longer find willing counterparties. The change spread through networks where participants learned prices and reputations from one another.
The unresolved contracts became a legal problem
After prices fell, the central issue was not whether tulips would continue to bloom. It was whether buyers had to honor agreements made at the peak. Because the contracts were decentralized, there was no single exchange authority that could close positions or impose a uniform settlement. Sellers wanted promised prices; buyers argued that circumstances had changed or tried to avoid payment altogether.
Municipal authorities and provincial institutions were drawn into disputes, but their responses were uneven. The Dutch Republic was a federation with strong local jurisdictions, not a unitary state issuing a single market rule. Proposals circulated to allow buyers to withdraw by paying a fraction of the agreed price—often reported as 3.5 percent—but historians caution against describing this as an instant nationwide solution. Local negotiations and court cases mattered more than the clean ending found in later retellings.
This legal uncertainty is one reason that estimates of total losses should be treated skeptically. A contract listed at a spectacular amount did not necessarily produce a cash payment of that amount, and an abandoned bargain did not necessarily bankrupt either party. Some arrangements were renegotiated; others went before local authorities; many are simply not preserved in records. The evidence supports distress and dispute among participants, not a reliable calculation of a national fortune that evaporated overnight.
It also explains why comparisons with modern crashes should be modest. Modern financial crises can transmit through banks, leverage, payment systems, and global securities markets. The tulip market was a smaller commercial network with limited systemic ties. The difference is not a defense of speculation. It is a reminder that the consequences of a price collapse depend on who is exposed, how contracts settle, and what institutions connect them.
The crash was real; a national catastrophe is not documented
The evidence leaves no doubt that the late-winter reversal harmed people who had made or depended on high-priced contracts. Sellers lost expected revenue, buyers faced contested obligations, and the flower’s market reputation changed. It would be wrong to sanitize the episode into a harmless misunderstanding. Yet the strongest version of the standard story—that the crash devastated Dutch commerce, threw families into ruin across the country, and ushered in a broad depression—does not match the best surviving evidence.
The Dutch Republic remained a powerful commercial and maritime state after 1637. Its economic life was not suspended by tulip trading, and there is no convincing record of a banking panic caused by bulbs. The University of Oxford’s discussion of tulipomania notes that the best evidence points to limited broader economic effects. That conclusion is not an argument that every loss was trivial; it is a conclusion about scale.
Why has the catastrophe story survived? Extreme examples are easier to remember than cautious qualifications. A narrative in which an entire nation trades houses for flowers is compact, visual, and morally satisfying. It has been useful to later critics of speculation, from nineteenth-century writers to modern commentators after market booms. Repetition has often done more than new evidence to preserve it.
There is an instructive parallel in the site’s account of the Black Friday gold panic of 1869: financial shocks have concrete causes, institutions, and participants, not just colorful symbols. Treating a tulip as the explanation for every 1637 loss is as unhelpful as treating gold itself as the explanation for every nineteenth-century financial crisis.
How a short episode became a permanent warning
“Tulip mania” was not born fully formed in 1637. Later writers selected anecdotes, price lists, and satirical scenes, then fitted them into a story about crowd psychology. Charles Mackay’s nineteenth-century Extraordinary Popular Delusions and the Madness of Crowds gave the tale exceptional reach in English. His prose was lively and influential, but modern historians have shown that it relied heavily on earlier accounts and repeated claims that archival work cannot always confirm.
Paintings and illustrated tulip books also helped fix the image of the era. They are not photographs of a single market event. A carefully painted flower could celebrate horticultural knowledge, domestic taste, trade, or the transience of beauty. The Fitzwilliam Museum’s material on tulipomania helps place such imagery within a broader visual culture rather than using every picture as proof of speculative frenzy.
Legend has a cost. It can make the Dutch Republic appear as a society that temporarily abandoned reason, instead of a society where collectors, growers, brokers, and local officials confronted a novel kind of contract dispute. It can also erase the botanical history of the flower itself. The broken tulip’s beauty was partly the result of a virus; the bulb trade’s volatility was partly the result of seasonality and informal contracting. Those specifics are more revealing than a generic warning about greed.
What tulip mania can actually teach about markets
Tulip mania remains useful, but only if the lesson is narrower than “people are foolish.” The episode shows how scarcity, status, and stories can create demand for objects whose practical use is secondary. It shows why agreements for future delivery can magnify both enthusiasm and fear. And it shows that prices are social facts: they depend on buyers believing other buyers will be present tomorrow.
It also teaches a lesson about historical evidence. Numbers survive unevenly. Satire travels more easily than a municipal court file. Later writers can turn a few memorable cases into a general law about an entire population. Good history has to ask what a source was trying to do, who produced it, and whether it records a completed transaction, an offer, a joke, or a moral warning.
The tulip market of 1637 was neither an invented event nor the collapse of a nation. It was a real speculative episode in a specialized and socially connected trade. Its afterlife became larger than the event itself because later generations needed a parable. Recovering the difference does not make the story less compelling. It makes the people who grew, traded, argued over, painted, and remembered tulips visible again.
Why the story still deserves careful reading
The most useful correction to the old legend is not to deny that a bubble occurred. It is to notice the specific mechanisms through which it did. A fashionable collecting culture, rare and hard-to-propagate varieties, winter contracts, and informal credit made a narrow market unusually sensitive to confidence. None of those ingredients required national delirium. They required only enough participants to believe that a named bulb would have a buyer at a higher price.
This is also why tulip mania belongs in the history of information. Participants relied on word of mouth, local gatherings, printed lists, and personal reputation. Prices could travel faster than reliable knowledge about who would settle an obligation. The same gap between a quoted value and a completed payment appears in many later episodes of speculation. It is a historical pattern, not proof that every price increase is fraudulent.
Readers should therefore be suspicious of exact, dramatic claims that lack a clear source trail: a bulb supposedly exchanged for a particular house, an entire town supposedly ruined, or a specific loss converted neatly into modern money. Such examples may have begun as reports, but their survival in popular writing does not make them representative. The more exact the number, the more important it is to ask whether it was an offer, a contract, an actual payment, or a later anecdote.
Sources and further reading
Rijksmuseum, “Tulip Fever 1637: Myth and Reality”
University of Oxford, “Tulipmania”
Cambridge Financial History Review, “Tulipmania: Facts, Myths and Their Uses”